
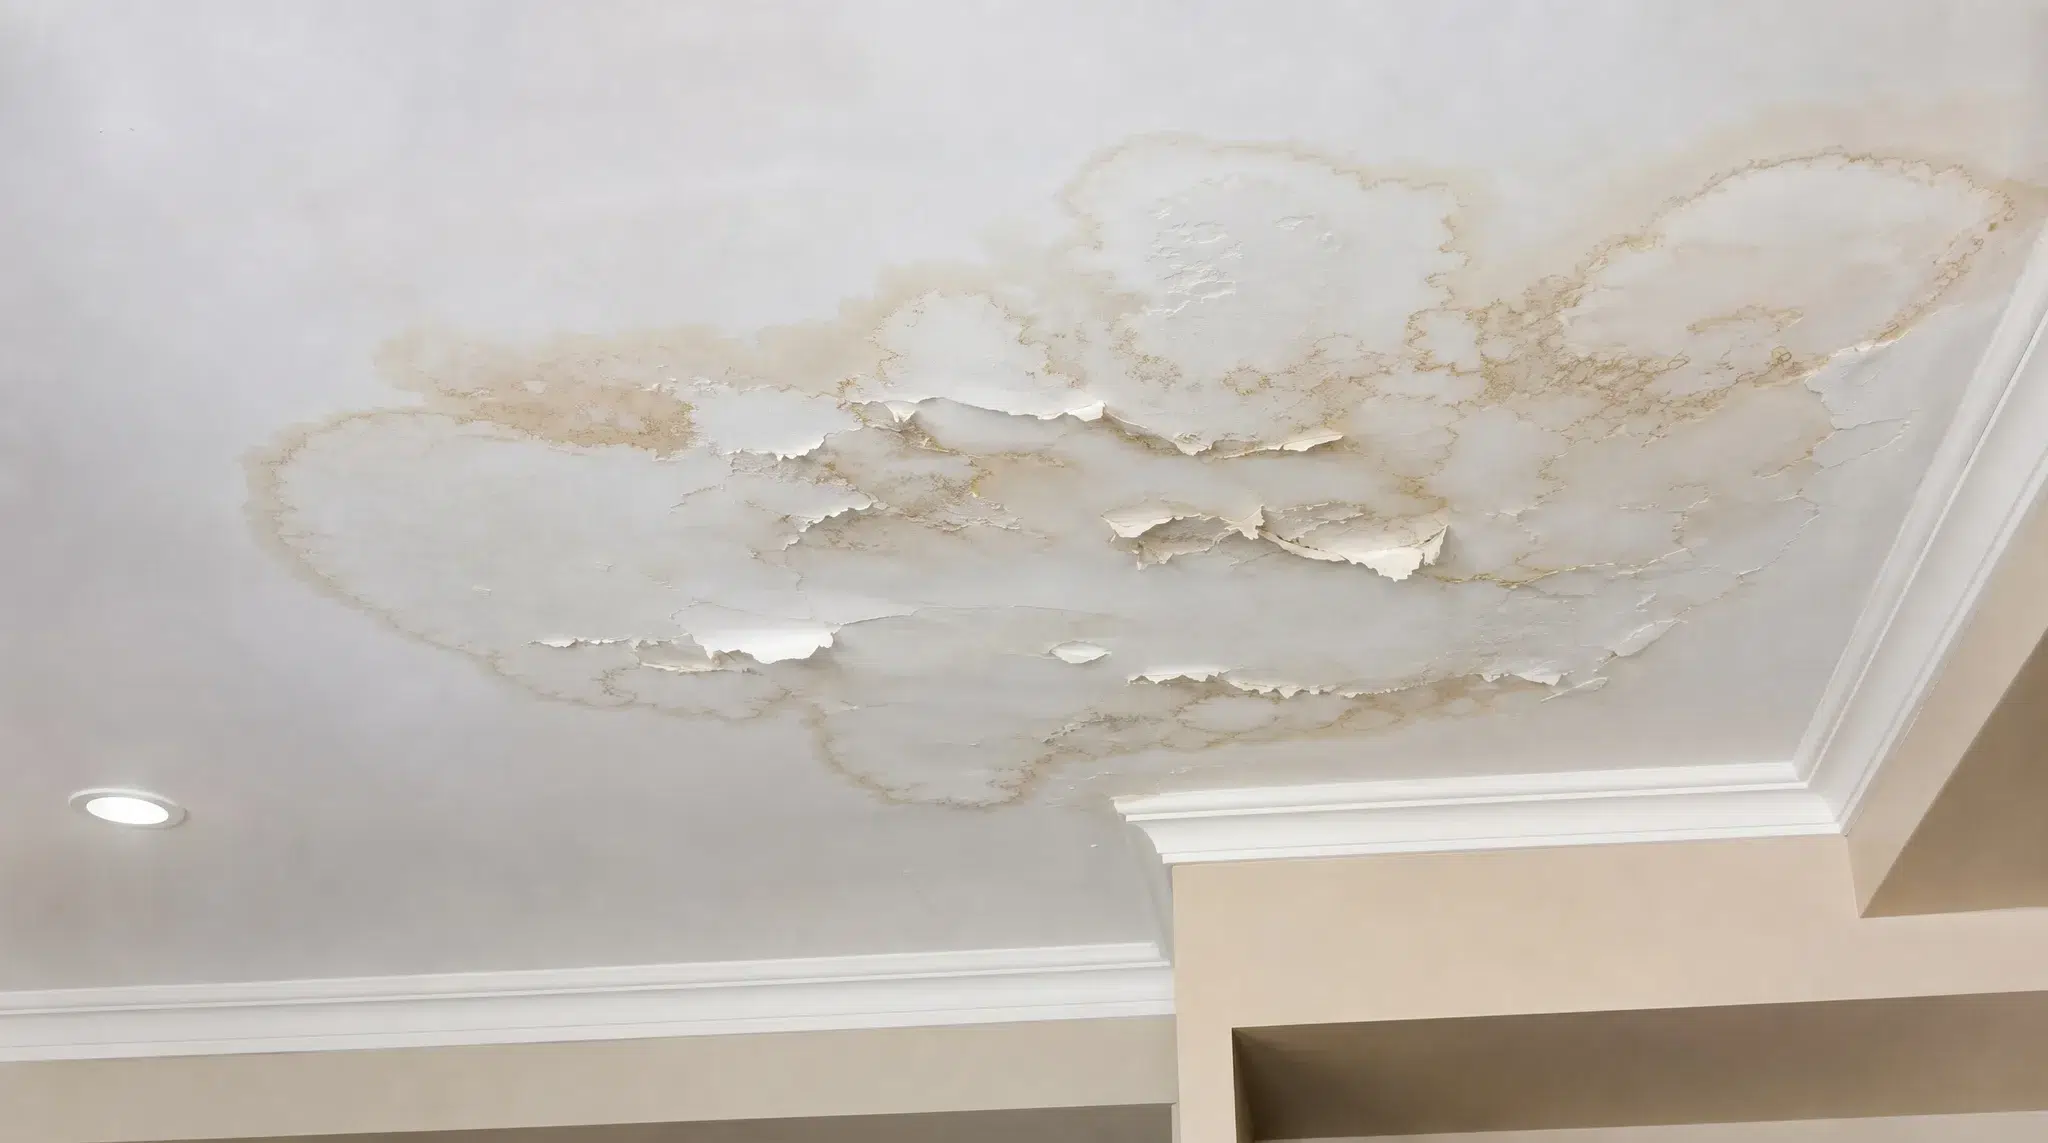
A pipe bursts while you’re away. Rainwater enters through a damaged roof. Or a crawlspace stays wet long enough for the flooring above it to soften. By the time you consider selling your Taylors, South Carolina, house, you’re facing questions about hidden damage, cleanup costs, insurance, and what a buyer will discover.
You can sell a house with water damage in Taylors, SC, without necessarily restoring every affected room first. The right approach depends on the source of the water, whether the property is safe, what your insurer will cover, and how much money you’ll receive after the sale.
Some homeowners dry and repair the house before listing. Others disclose the condition and market it as-is or request a direct offer. This guide explains the choices, including Greenville County floodplain and permit considerations, South Carolina disclosure rules, and a realistic financial comparison. GSP Investors LLC considers damaged houses for direct purchase throughout Upstate South Carolina.
Can You Sell a Water-Damaged House As-Is in Taylors?
Yes. South Carolina does not generally require a home to be restored to like-new condition before its owner sells it. A buyer may agree to accept existing water damage, provided the transaction complies with applicable laws, disclosures, orders, and contract terms.
But an as-is listing does not make moisture, unsafe wiring, or weakened floors irrelevant. Serious damage can limit the pool of financed buyers and change insurance availability. A property with an active leak also risks deteriorating while under contract.
Start by identifying what caused the water, whether it has stopped, and which materials are affected. That matters more than a rough estimate based on visible staining. Homeowners considering alternatives can review selling a house in Taylors directly, without first assuming that every damaged surface requires replacement.
Common Sources of Water Damage in Taylors Homes
The source determines cleanup priorities and may determine insurance coverage. Four situations that appear similar in photographs can have different financial consequences.
Burst supply pipe or appliance leak. A sudden plumbing failure may soak cabinets, flooring, and lower walls. Even after the pipe is repaired, trapped moisture can remain beneath finished materials.
Roof or window intrusion. Water can travel along framing before appearing as a ceiling stain. Repairing drywall without correcting the roof or flashing may allow damage to return. Our Spartanburg bad-roof guide addresses roof-related selling decisions separately.
Surface flooding or rising water. Rain runoff, overflowing waterways, and water entering from outside at ground level raise different insurance and contamination questions from an interior pipe leak.
Drain or sewer backup. Wastewater can present contamination hazards and may require specialized removal rather than ordinary household cleanup. Do not assume a standard homeowners policy covers a backup; check whether an endorsement applies.
A damp crawlspace may also result from drainage, groundwater, condensation, or plumbing. A qualified inspection can distinguish the likely cause before you purchase an expensive remedy.
What Should You Do Before Showing the House?
Protect people first. If standing water may contact electrical equipment, avoid entering the affected area until qualified personnel confirm it’s safe. Treat sewage and unknown floodwater as potentially contaminated. Never enter an unstable or visibly compromised structure merely to photograph it.
When safe, stop the source if you can: shut off the appropriate water supply, arrange an emergency plumbing repair, or prevent further rain intrusion. Photograph affected areas before removing materials, and keep receipts for emergency work.
Notify your insurer promptly when a potentially covered event occurred. The South Carolina Department of Insurance’s disaster guidance recommends documenting losses and preserving repair records. Discuss disposal of damaged materials with the insurer when a claim is likely.
Don’t hide moisture damage with fresh paint or new carpet. Instead, explain which areas have been assessed, what work was done, and what remains uncertain. Buyers are more likely to evaluate a clearly documented condition than an unexplained musty smell.
How Quickly Can Mold Develop After Water Damage?
Water removal is not the same as drying. Moisture can remain in insulation, wall cavities, subfloors, and crawlspaces after the visible water disappears.
The U.S. Environmental Protection Agency advises drying water-damaged areas and materials within 24–48 hours to help prevent mold growth. That is a prevention guideline, not a promise that a house will be mold-free if drying occurs within that window.
If mold is visible or suspected, address the moisture source before cosmetic repairs. EPA mold-cleanup guidance notes that porous materials can be difficult to clean and may require removal. Extensive contamination, sewage, and certain health or safety circumstances warrant professional attention.
A seller should not declare that mold is absent merely because a room no longer smells damp. Equally, discoloration alone does not identify a particular species or establish the scope of an infestation. Describe what is known, provide available professional findings, and avoid unsupported assurances.
How to Identify Hidden Water Damage Before Selling
The wet area you can see may be smaller than the affected area. Water sometimes travels beneath vinyl flooring, through insulation, along joists, or inside a wall. A restoration professional may use appropriate moisture measurements and targeted investigation to develop a drying or removal plan.
Ask for written documentation explaining the affected areas, recommended demolition or drying, and whether structural, electrical, or HVAC specialists are needed. If the floor feels unstable or framing appears damaged, consider a qualified structural evaluation rather than allowing a general cleanup quote to stand in for engineering advice.
Request separate estimates for stopping the leak, removing wet materials, drying, restoring finishes, and any structural work. Combining everything into one unexplained total makes it difficult to compare repair bids or negotiate a sale. Our Greenville major-repairs article offers a broader renovation-versus-sale comparison.
Selling a Taylors House With Previous Flood Damage
Taylors is a census-designated area, not an incorporated City of Taylors. Taylors is an unincorporated community in Greenville County. However, a Taylors mailing address does not, by itself, establish which permitting or floodplain authority governs a specific property. Confirm the parcel’s jurisdiction before beginning regulated repairs. Confirm the actual jurisdiction and tax parcel before relying on a local department’s requirements.
For unincorporated areas, Greenville County Floodplain Administration explains how owners can request a property-specific flood-hazard determination. You can also check FEMA’s Flood Map Service Center.
A mapped flood zone is not a record of every past water event, and being outside a mapped high-risk area doesn’t mean a home cannot flood. If repairs concern a property within a regulated floodplain, ask the floodplain administrator whether additional permits or substantial-damage requirements may apply.
Document past water entry, known drainage problems, and repairs. Don’t tell buyers that a property has never flooded unless your available knowledge supports that claim.
Does Homeowners Insurance Cover Water Damage in South Carolina?
The cause of the loss is crucial. Some sudden, accidental plumbing losses may be covered under a homeowners policy, depending on its terms. Gradual leakage, deterioration, or inadequate maintenance may be excluded or limited. Sewer-backup coverage may require a separate endorsement.
The most important distinction is between an internal water loss and flooding from outside. The South Carolina Department of Insurance explains that standard homeowners insurance generally does not cover floodwater entering from streets, overflowing waterways, or similar surface flooding. That ordinarily requires separate flood insurance.
Check your declarations page, policy wording, deductible, exclusions, and any water-damage endorsements. Ask the insurer to identify the cause-of-loss determination and applicable limits in writing. Do not include an anticipated claim payment in your sale calculations until you understand what is approved.
If the claim is denied, ask for the written explanation and review the available appeal or complaint options. An insurer’s denial is not proof that the damage must be concealed or that the house cannot be sold.
Can You Sell While a Water-Damage Claim Is Still Open?
Potentially, but coordinate with your insurer and closing attorney. Determine whether the claim has been accepted, what payments remain outstanding, and whether mortgage-lender interests affect the settlement funds.
The purchase contract should identify whether the seller will complete any approved work, provide a negotiated price adjustment, or retain responsibility for specific claims. Insurance benefits do not automatically transfer with the deed. Avoid promising recoverable depreciation or claim proceeds to a buyer without confirming the applicable policy and legal requirements.
Retain adjuster reports, photographs, invoices, and communications. If insurance funds are included in negotiations, avoid counting them twice—once as repair reimbursement and again as extra sale proceeds.
Do Water-Damage Repairs Require Permits in Taylors?
A cleanup company removing water may perform tasks different from a contractor rebuilding walls, changing plumbing, or replacing electrical components. Permit requirements depend on the type of work and jurisdiction.
For properties governed by Greenville County, its Building Safety and Permitting Department identifies regulated structural alterations and electrical, plumbing, mechanical, and other work that may require permits. Ordinary drying does not automatically mean every project needs a building permit, but reconstruction can trigger additional obligations.
Verify which authority governs the parcel, whether structural repairs need plans, who will apply for permits, and which inspections must be completed. If the house is in a regulated floodplain, contact Greenville County Floodplain Administration before major reconstruction.
Don’t advertise water-damage restoration as fully permitted or approved if the contractor has not supplied supporting records.
Must You Disclose Previous Water Damage When Selling in South Carolina?
South Carolina’s Residential Property Condition Disclosure Act generally requires a prescribed disclosure statement for covered transactions. The form addresses roofs, structural components, plumbing, water and sewage systems, and relevant property conditions.
The state’s Residential Property Condition Disclosure Statement includes questions concerning water intrusion and damage, drainage, flooding, and related conditions. Answer based on what you actually know. Keep reports documenting the source, restoration, and any recurring problem.
Certain transactions are exempt from the statement requirement. However, an as-is agreement does not automatically eliminate applicable disclosures or permit intentional misrepresentation. Nor does selecting “No Representation” provide a way to hide a known defect.
If you discover material new information after completing a statement, the law may require correction. Consult a South Carolina attorney when the loss history, claim documents, or transaction terms create uncertainty.
Can Water Damage Prevent Mortgage Approval or Insurance Coverage?
Yes, significant unresolved water damage can affect appraisal and loan conditions. Unsafe wiring, weakened structural components, active intrusion, or extensive deterioration may prompt specialist evaluation or repairs before a lender will approve financing.
For FHA-insured transactions, HUD’s Single Family Housing Policy Handbook 4000.1 provides the relevant property standards. A lender’s specific condition is different from a buyer’s preference for cosmetic improvements.
The buyer may also struggle to obtain acceptable homeowners insurance if water is still entering the building or required mitigation remains incomplete. Ask for the actual written lender or insurance condition before agreeing to repairs or credits. A price reduction alone may not solve a condition that must be corrected before closing.
If water damage surfaces during a buyer’s inspection, review contract deadlines and repair requests carefully. Our Simpsonville failed-inspection guide explains those negotiations in detail.
Three Ways to Sell a Water-Damaged House in Taylors
1. Complete Restoration and List Normally
Restoration may attract buyers who want finished living space and documentation that the moisture source has been corrected. But you fund removal, drying, rebuilding, permits, and holding expenses upfront. Hidden damage can enlarge the scope.
2. List the Property As-Is
An agent can market the house with the known water-damage history and supporting reports. You may avoid substantial renovation expenses, although the price will reflect repairs and some financed buyers may face restrictions. An as-is sale still requires appropriate disclosures and contract compliance. See our guide to selling without a Realtor in Upstate.
3. Request a Direct Cash Offer
A direct purchaser may evaluate the property with its remaining damage and consider repairs after closing. The offer generally accounts for restoration, resale expenses, holding costs, and risk; it may be lower than a successful repaired sale price. Compare actual written terms using the company’s home-selling options guide.
Taylors Example: Restore the House or Sell As-Is?
Imagine a hypothetical Taylors home with a previously stopped kitchen supply-line leak. Flooring, cabinets, and part of the subfloor need evaluation and work. The owner has not assumed any insurance payment.
| Estimated item | Restore & list | List as-is | Direct cash sale |
|---|---|---|---|
| Selling price | $286,000 | $252,000 | $219,000 |
| Drying, repairs, and restoration | $33,000 | $0 | $0 |
| Selling and closing expenses | $17,500 | $15,000 | $0* |
| Holding expenses | $6,000 | $3,000 | $1,000 |
| Evaluation and documentation | $2,000 | $2,000 | $2,000 |
| Estimated proceeds before debt payoff | $227,500 | $232,000 | $216,000 |
Hypothetical illustration, not Taylors market averages, contractor quotes, or guaranteed offers. The direct-sale column assumes the buyer pays ordinary seller closing expenses. Insurance proceeds, mortgages, liens, taxes, and other required payoffs are excluded.
Here, listing as-is produces $4,500 more than restoring and listing. A direct sale produces $16,000 less than the as-is listing but removes the owner’s need to manage restoration. Actual estimates, additional wet materials, future insurance payments, and time on market could change every result. The point is to compare net proceeds, not only the repaired selling price.
What If the House Is Vacant or You Live Out of State?
Water damage can worsen unnoticed in an empty home. Confirm vacancy-related insurance requirements, arrange property checks, and maintain necessary utilities or professional protection while awaiting a sale. Don’t assume a house is safe because the water has visibly receded.
If you live elsewhere, identify a reliable local contact who can admit qualified inspectors, document repairs, and respond to new damage. Inherited properties may also require authority from the owner or estate representative before a sale can proceed. Our guide to inherited houses in Greenville covers related ownership considerations.
Checklist Before Selling Your Water-Damaged House
- Stop active water intrusion and address electrical, structural, or contamination hazards.
- Photograph the loss and retain invoices, restoration notes, and relevant insurer communications.
- Identify the source—plumbing, roofing, drainage, floodwater, or sewer backup.
- Evaluate remaining moisture and seek qualified advice for mold or structural concerns.
- Check insurance coverage and whether an open claim affects proposed closing terms.
- Verify floodplain status using your parcel and the appropriate local authority.
- Confirm permits for any regulated repairs or reconstruction.
- Complete disclosures accurately and update them if material new information emerges.
- Compare net proceeds after repair costs, selling expenses, and continued ownership costs.
- Review the buyer’s terms, including financing, inspections, proof of funds, and closing obligations.
How GSP Investors LLC Evaluates Water-Damaged Houses in Taylors
GSP Investors LLC considers houses needing repairs in Taylors and surrounding Upstate communities. Owners can request a no-obligation evaluation without first completing a full restoration.
Share the address, what caused the water damage, when it occurred, any remaining moisture or contamination, and available insurance or contractor records. The company reviews the property’s condition and determines whether a direct purchase is feasible. If an offer is made, compare its price, contingencies, and closing obligations with your other options.
A direct sale doesn’t automatically eliminate disclosure duties, government orders, or title requirements. Learn more about how GSP Investors buys houses, the company, and homeowner reviews.
Frequently Asked Questions About Selling a Water-Damaged House in Taylors, SC
1. Can I sell my house with water damage in Taylors, SC?
Yes. Buyers may consider a property with water damage as-is. The condition, disclosure obligations, financing, and contract terms affect the sale.
2. Do I have to repair all water damage before selling?
Not necessarily. Some buyers accept unfinished restoration, although safety issues, lender conditions, or government orders may require attention.
3. Will homeowners insurance cover water damage from a burst pipe?
Possibly. Coverage depends on whether the loss is covered, the policy’s exclusions, deductible, and circumstances of the leak.
4. Is flood damage covered by standard homeowners insurance?
Generally not. Flooding from outside surface water normally requires separate flood insurance, subject to policy terms.
5. Can I sell a house with mold after water damage?
Potentially. Disclose known conditions as required and obtain qualified advice about ongoing moisture, contamination, and buyer safety concerns.
6. Do I need permits to repair water damage in Taylors?
Some structural, plumbing, electrical, or mechanical work requires permits. Confirm jurisdiction and scope with the applicable building department.
7. Must I disclose previous water intrusion in South Carolina?
Applicable seller disclosure rules address water-related property conditions. An as-is sale doesn’t automatically eliminate those obligations.
8. Can I sell while a water-damage insurance claim is open?
Potentially. Clarify claim funds, repair responsibilities, and lender interests with your insurer and closing attorney before agreeing to terms.
9. Is it better to restore a water-damaged house or sell as-is?
Compare written repair estimates and realistic offers after selling, carrying, and closing expenses. The highest price may not produce the best net result.
10. Will GSP Investors LLC consider buying my water-damaged house?
Yes. GSP Investors LLC considers water-damaged homes in Taylors. Any purchase depends on the property’s condition and agreed terms.
Compare Your Options Before Starting Water-Damage Restoration
A wet floor or stained wall doesn’t tell the whole story. Before committing to an expensive restoration, determine whether the source is fixed, what remains affected, and whether insurance or buyer financing changes the decision.
Restoration may produce a higher sale price. An as-is listing may preserve more cash by avoiding major upfront work. A direct sale is another option when you prefer not to manage repairs. Use written assessments, realistic offers, and net proceeds to choose.
To explore a direct purchase, request a no-obligation cash offer from GSP Investors LLC or contact the team at (864) 671-1011.
This guide provides general information, not legal, insurance, environmental, engineering, or financial advice. Consult qualified professionals about your property’s condition, coverage, disclosures, and selling obligations.